Buying a vehicle described as a "commercial" or "crew van"? Before assuming you can reclaim the VAT and enjoy van tax treatment, check the details.
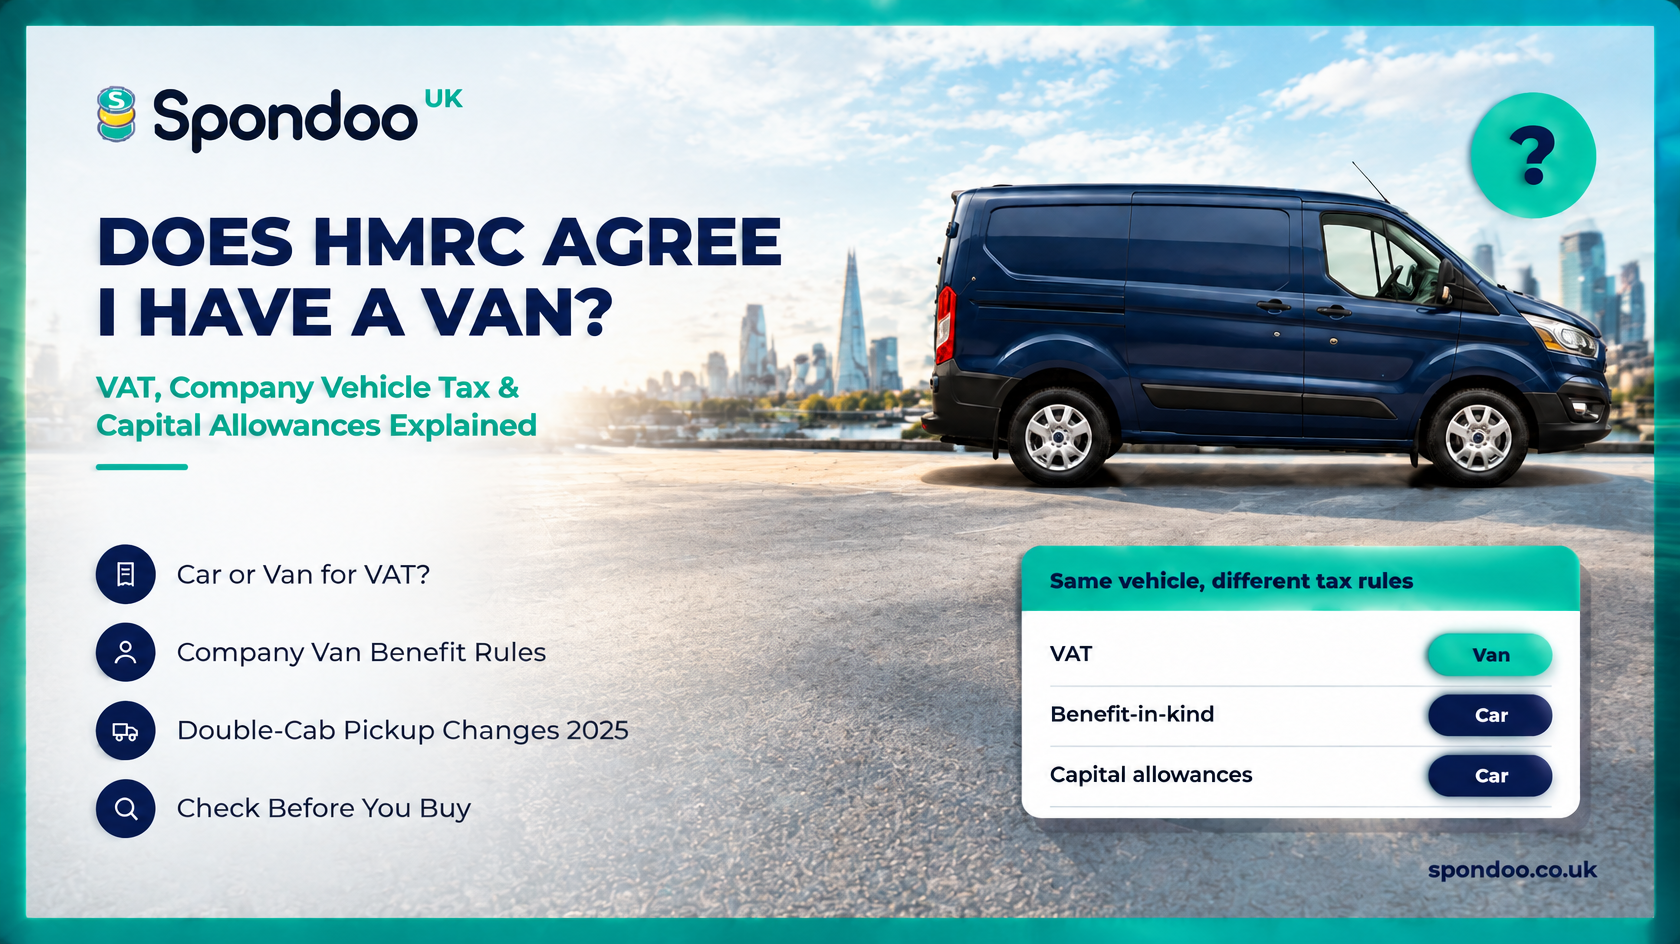
A vehicle can qualify as a van for VAT but be treated as a car for other taxes. The distinction matters when buying through your business or providing a vehicle to a director or employee.
HMRC's car-derived vans and combi vans list identifies specific vehicles as cars or vans for VAT input tax deduction purposes.
For example, it lists:
| Vehicle and specification | VAT classification |
|---|---|
| Ford Fiesta three-door van | Van |
| Citroën Dispatch panel van | Van |
| Citroën Dispatch window van | Car |
| Fiat Scudo Combi 2.0JTD 16v SX, six seats | Car |
The exact variant matters. Two vehicles with the same model name can have different classifications.
Crucially, the linked list dates from May 2015. It should not be treated as a complete guide to current models or as confirmation of the position for every tax.
VAT on buying a car is generally blocked, subject to limited exceptions. Commercial vehicles fall outside that car purchase restriction, although normal VAT recovery conditions still apply.
HMRC's VAT definition considers passenger accommodation, rear side windows and specific exceptions—including vehicles with a payload of at least one tonne. Simply buying a vehicle for work does not establish your entitlement to recover VAT. Private use and your business's VAT position also need consideration.
For employment benefits, HMRC examines the vehicle's construction and whether it is primarily suited to carrying goods. Using it to transport tools does not, by itself, settle its classification.
Qualifying vans can receive favourable treatment where use is restricted to business travel and commuting, with any other private use insignificant. Broader private use can trigger a taxable van benefit.
Most double-cab pickups are now treated as cars for benefit-in-kind purposes from 6 April 2025, even where they remain commercial vehicles for VAT.
Employers that purchased, leased or ordered a qualifying pickup before that date may retain the previous benefit treatment until the earliest of disposal, lease expiry or 5 April 2029.
Capital allowances changed separately from 1 April 2025 for Corporation Tax and 6 April 2025 for Income Tax. Most double-cab pickups now fall within the car rules, affecting purchase tax relief. Separate transitional provisions apply; the benefit-in-kind protection through 2029 does not extend to capital allowances.
Send Spondoo the exact model, specification, seating layout, payload, purchase or lease dates and intended business and private use.
We can review the VAT, purchase tax relief and company vehicle benefit position together, so you understand the tax cost before committing.
Thinking of buying a van through your business? Speak to Spondoo before placing your order.