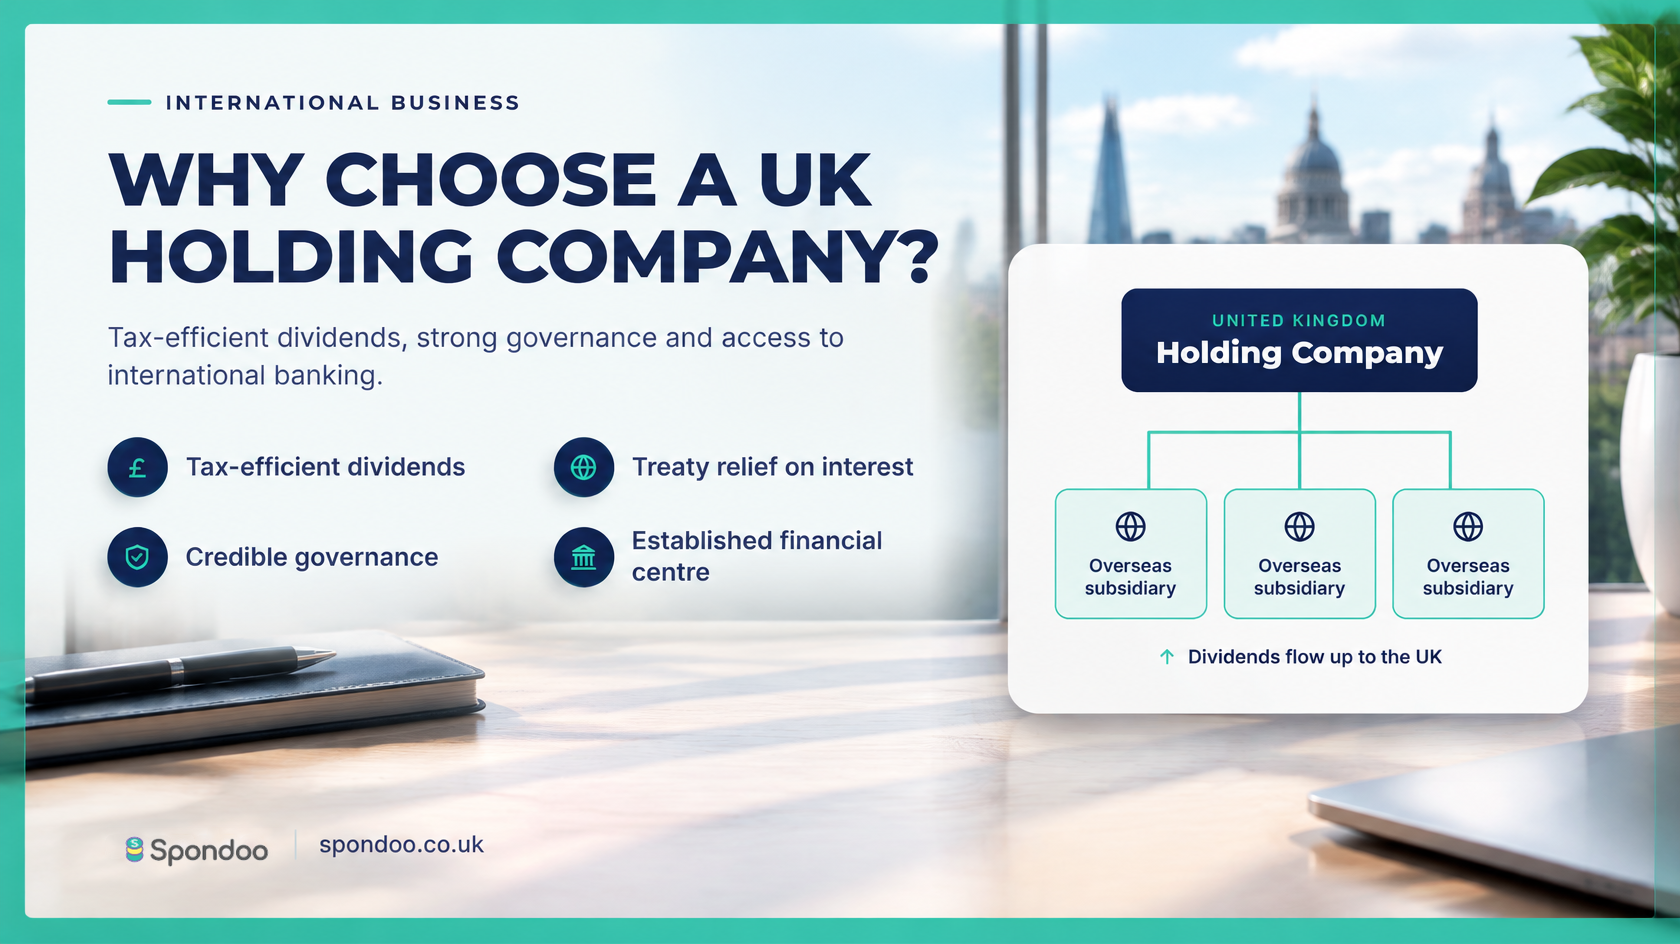
The UK can be an attractive location for a holding company—even where its ultimate owners, shareholders and trading subsidiaries are based overseas. It combines favourable dividend tax treatment with an established legal system and access to international banking.
Most dividends received by UK companies, including dividends from overseas subsidiaries, are exempt from UK corporation tax, subject to the relevant conditions. Ordinary dividends paid onwards to overseas shareholders generally carry no UK withholding tax, without requiring a double taxation agreement. Foreign withholding taxes and taxes in the shareholder’s country still need to be considered.
The UK’s extensive treaty network can also reduce or eliminate withholding tax on interest paid overseas. However, relief is not automatic: UK-source yearly interest generally attracts 20% withholding unless an exemption or treaty relief applies. The particular treaty must be checked, and HMRC clearance is normally required before applying a reduced or zero rate.
A holding company can operate with a relatively limited function, but it needs a genuine commercial purpose and appropriate governance. Tax residence, beneficial ownership and treaty anti-abuse rules remain relevant—particularly where decisions are made overseas. UK incorporation alone does not guarantee treaty benefits.
Normal compliance also applies, including annual accounts, confirmation statements, ownership disclosures and tax returns where required. A UK holding company is therefore potentially tax-efficient, rather than free from filing obligations.
The UK offers a wide choice of banks and financial service providers serving international businesses. Account opening remains subject to eligibility and due diligence, with additional checks often required for overseas owners.
For an appropriately structured international group, these features can make the UK a compelling base for holding investments, receiving profits and distributing dividends. The key is to assess the whole structure, including the rules in each subsidiary’s and shareholder’s jurisdiction.
Whether you are building an international group or reviewing an existing structure, contact Spondoo UK to discuss whether a UK holding company is right for your business. Speak to our team about the tax position, company setup and ongoing accounting and compliance requirements, and take the next step with a clear understanding of the benefits and obligations.